Table of Contents
TL;DR
There is no bank balance that determines readiness for parenthood. But having emergency savings, health coverage, a clear leave-and-childcare budget, and financial protection for dependents can reduce avoidable stress. A practical starting goal is several months of essential expenses plus enough cash to cover expected medical and early baby costs without relying on high-interest debt.
The Question With No Perfect Answer but Clear Planning Targets
There is no perfect financial time to have a baby. Income can change. Housing costs can rise. Childcare plans can fall through. Even families with strong savings may face expenses they did not predict.
That does not mean money planning is pointless. A baby changes cash flow immediately and can affect work, insurance, housing and long-term saving for years. Preparing in advance helps parents spend less time reacting to bills during an already demanding period.
The goal is not to reach financial perfection before becoming a parent. It is to avoid entering early parenthood with no cash cushion, no understanding of medical costs and no plan for reduced income or childcare.
Think of the following targets as readiness checks rather than permission slips.
Readiness Target #1: Build an Emergency Fund Before Birth
A new baby creates several financial unknowns at once. There may be out-of-pocket medical expenses, unpaid or partially paid leave, extra travel to appointments, feeding costs or a need for more help at home.
A six-month emergency fund is a strong target before birth, especially when one income may temporarily fall or childcare will soon become a major recurring expense. Calculate it using essential monthly costs, not your entire lifestyle budget.
For example:
| Essential Household Expenses | Six-Month Emergency Fund Target |
| $3,500 per month | $21,000 |
| $4,500 per month | $27,000 |
| $6,500 per month | $39,000 |
Not every family can save six months before a child arrives. When that amount is out of reach, begin with one month of essential expenses, then continue building toward three months and beyond. A smaller emergency fund is still far better than relying entirely on a credit card.
Keep this money accessible. Savings intended for hospital bills, lost wages or urgent needs should not be placed in volatile investments that might fall when you need cash.
Readiness Target #2: Know Your Health Coverage and Medical Exposure
Health insurance does not make childbirth free. It can, however, dramatically reduce the risk of an unaffordable bill.
HealthCare.gov states that Marketplace and Medicaid plans cover pregnancy and childbirth, and that maternity and newborn care are essential health benefits for qualified health plans. Employer coverage varies by plan design, networks, deductibles and cost-sharing rules, so parents should read their own plan documents carefully.
A 2025 KFF analysis of women enrolled in employer-sponsored insurance found that pregnancy, childbirth and postpartum care averaged $20,416 in total healthcare spending, including $2,743 in out-of-pocket costs. Newborns in the analysis averaged an additional $5,820 in total spending and $475 out of pocket during their first months of enrollment.
Average figures cannot tell you what your own birth will cost. Before the due date, confirm:
- Your obstetrician and planned delivery hospital are in network.
- Your deductible, coinsurance and family out-of-pocket maximum.
- How newborn enrollment works after birth and what neonatal intensive care coverage would look like under your plan.
Set aside at least the out-of-pocket amount you reasonably expect under your insurance plan, in addition to general emergency savings. When possible, plan closer to the out-of-pocket maximum than to an optimistic estimate.
Readiness Target #3: Understand Leave, Income and Childcare Before You Need Them
Many parents know their salary but do not know what happens to it during parental leave.
Under the federal Family and Medical Leave Act, eligible employees of covered employers may take up to 12 workweeks of job-protected leave for the birth of a child and bonding. The leave may be unpaid. Eligibility generally requires at least 12 months with the employer, at least 1,250 hours worked in the prior 12 months and a covered work location. State law or employer benefits may provide stronger paid-leave options.
Before planning a baby budget, ask each employer for the written leave policy. Find out how many weeks are paid, what percentage of pay continues, how health premiums are handled during leave and when a parent expects to return to work.
Childcare deserves the same attention. Child Care Aware of America reported an average annual childcare price of $13,184 in 2025, while center-based infant care nationally was roughly $15,000 to $15,700 annually, depending on the calculation method. In many high-cost areas, local infant care can be much higher.
A family expecting $1,300 per month in infant care should test that expense in the budget before birth. Redirect that amount into savings for several months. This builds a baby fund while showing how the household feels with the future childcare cost already removed from monthly spending.
Readiness Target #4: Protect the Income Your Child Will Depend On
When a child will depend on your income or unpaid caregiving work, life insurance becomes part of financial preparation.
Term life insurance provides coverage for a set period and pays a death benefit when the insured person dies during that term. The National Association of Insurance Commissioners notes that term coverage can be appropriate for a primary wage earner or a spouse relied upon for mortgage payments, and is generally less costly in younger years than permanent coverage.
A quick income multiple can be a starting estimate, but it should not be treated as the final answer. Calculate the actual need: remaining mortgage or rent support, childcare, debts, education goals, final expenses and the income or services a surviving parent would need to replace. Subtract existing assets and any coverage already in place through work.
A stay-at-home parent may also need coverage. Replacing childcare, transportation, household management and other unpaid work can create a major cost for the surviving family.
Premiums depend on age, health, coverage amount, term length and insurer underwriting. Compare actual quotes instead of relying on a generic monthly-price estimate.
Recommended: Reduce High-Interest Consumer Debt
Parents do not need a debt-free balance sheet before having a child. A mortgage, student loan or manageable car loan may be part of ordinary family life.
High-interest credit card debt is different. It reduces monthly flexibility at the exact time expenses are likely to increase. A family entering parenthood with $8,000 on a card charging a high annual interest rate may have less room for medical bills, unpaid leave or childcare deposits.
Before the baby arrives, prioritize expensive revolving balances where possible. At minimum, stop the balance from growing, create a repayment plan and avoid financing routine baby purchases through debt.
Do not pause every long-term financial priority blindly. When a workplace retirement match is available, review the value of continuing enough contributions to receive it while managing debt and preparing cash reserves.
Your Financial Readiness Check
Savings alone do not tell the complete story. A family with $25,000 in cash and $35,000 in high-interest debt is in a different position from a family with $25,000 in cash, retirement savings and no consumer debt.
List your savings, retirement accounts, investments, property equity and other assets. Then subtract mortgage balances, student loans, auto loans, credit cards, medical debt and any other liabilities.
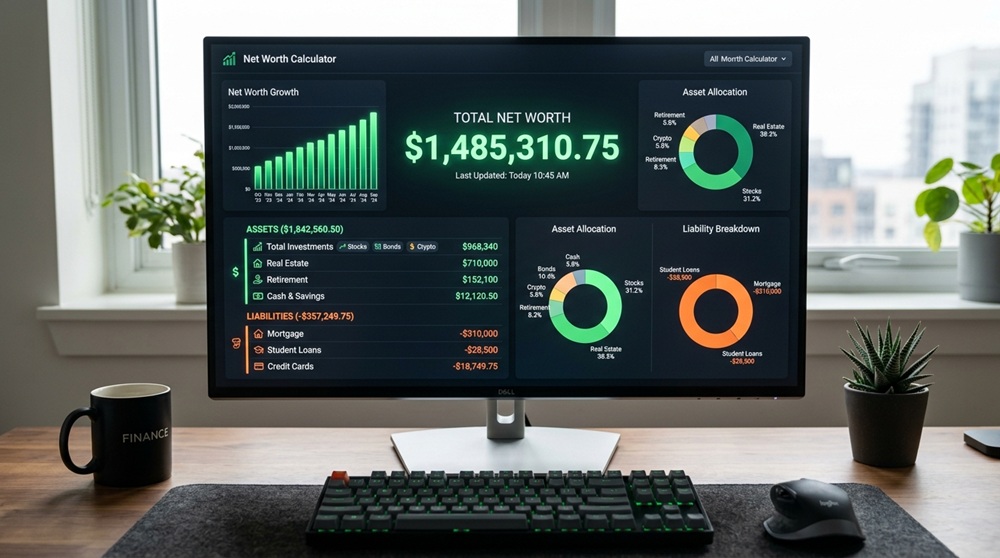
Before building the baby budget, check your net worth first. The calculator lets you enter assets and debts, see your current net worth instantly and identify how much of your financial position is liquid cash versus long-term or borrowed value.
Then add three separate baby-readiness figures beside your net worth: emergency fund months, expected medical out-of-pocket cost and estimated monthly childcare or income-loss amount. Net worth shows your starting position. These cash-flow figures show how prepared you are for the first year.
For further practical resources on tracking assets, debt and family financial progress, visit NetlyWorth.
Prepared Is Different From Perfect
Having a baby is not a decision that fits neatly into a spreadsheet. Financial preparation cannot remove every uncertainty, and families begin parenthood from many different starting points.
Still, clear numbers reduce preventable pressure. Build the cash cushion you can, understand health coverage, price childcare locally, review leave income, protect dependents and reduce expensive debt. You do not need a perfect net worth number. You need a plan strong enough to help your family handle the changes ahead.